Deciding whether to lease or finance your new Chevrolet depends on your routine, whether that involves a 32-minute daily commute down US-30 or running weekend errands from Michigan City to Southlake Mall. Exploring both payment options helps drivers across Valparaiso, Crown Point, and Schererville match their household budget to their true mileage needs. As the team at Chevrolet of Merrillville, our long-standing presence in the community has cemented our role as a reliable, long-term automotive partner for drivers here and in nearby areas. We pair deep local knowledge with trusted experience, explicitly highlighting our expertise in servicing and maintaining Chevrolet vehicles to keep you safely on the road long after the paperwork is signed.
Key Takeaways (TL; DR)
Getting the keys to a new vehicle should be an exciting milestone, not a stressful ordeal. For drivers navigating Northwest Indiana, understanding how auto loans and leases work is the most effective way to secure terms that actually fit your household budget. Whether you are eyeing a fuel-efficient SUV or a capable truck, here is a quick summary of the financing essentials you need to know.
- Your Credit Score Sets the Tone: Your credit history directly influences the interest rate you receive on any auto loan. A stronger score can significantly reduce the total interest paid over time, freeing up cash for weekend errands around Southlake Mall.
- GM Financial Streamlines the Process: Chevrolet's primary lending partner provides competitive rates and flexible terms tailored to different financial situations. Drivers can typically get pre-approved online, which saves valuable time before you ever make the drive down US-30.
- Financing Builds Equity, Leasing Offers Flexibility: Choosing a traditional loan means you will eventually own your Chevrolet Equinox outright. Leasing acts more like a long-term rental, generally keeping your monthly payment lower but enforcing an annual mileage limit.
- Options at the End of a Lease: Once your two- or three-year term is complete, you are not locked into one path. You can buy the vehicle at its predetermined residual value, return it entirely, or trade up into the newest model.
- Special Discounts Reduce Costs: Chevrolet frequently runs incentive programs for active-duty military, first responders, and recent college graduates. Qualifying for one of these offers can take a noticeable bite out of your down payment.
- Preparation is Non-Negotiable: Arrive at the finance desk with your driver's license, current proof of insurance, and recent pay stubs. Nailing down a firm budget beforehand makes it much easier to lock in a comfortable payment for your daily commutes along I-65.
How Auto Financing Works for Your Next Chevrolet
Financing simply means borrowing the purchase amount for your vehicle through a bank, a local credit union, or GM Financial. You repay that principal plus interest on a set schedule, which is called the loan term-typically running anywhere from 36 to 72 months depending on your contract. For families around Merrillville, this setup makes it much easier to drive off in a spacious Chevrolet Tahoe for weekend errands at Southlake Mall without needing the entire purchase price in cash upfront. Most importantly, every monthly payment you make builds equity, which is the actual cash value of the vehicle that belongs to you rather than the lender.
Once your final payment clears, the financial institution signs over the title, and the Chevrolet is completely yours. Unlike a lease, traditional financing comes with absolutely zero mileage limits. If your daily routine involves a longer commute up the I-65 corridor toward Chicago or frequent weekend trips hauling gear to Hidden Lake Park, you will never have to track your odometer or stress about mileage overage penalties. Securing an auto loan is the most practical route if you plan to keep a truck like the Silverado 1500 for the long haul and want the ultimate freedom to add custom accessories.
How Does GM Financial Work for Your Next Chevrolet?

GM Financial operates as the official lending arm for Chevrolet, streamlining how you pay for your vehicle directly through the dealership. What this means for local drivers is that you can lock in competitive purchase and lease programs without juggling separate outside bank loans while out shopping near Southlake Mall.
Once you zero in on a 2027 Chevrolet Equinox SUV or a capable Silverado 1500 truck, you can initiate the process from home using a secure online pre-approval application. Consider the time savings: completing your application online takes just a few minutes on your couch, potentially saving you over an hour of paperwork once you arrive at our Merrillville showroom just off the US-30 corridor.
During the review process, GM Financial evaluates factors like your income and credit history to build a tailored lending package. Keep in mind that specific incentives-such as promotional Annual Percentage Rates (APRs), down payment assistance, or lease loyalty bonuses-will vary by credit tier. Because they work directly with the manufacturer, they frequently provide flexible terms that independent lenders simply cannot match.
Understanding a Chevrolet Lease Agreement
Leasing a new Chevrolet operates much like a structured, long-term rental, typically lasting between 24 and 36 months. Instead of borrowing money to cover the entire sticker price of the vehicle, you only pay for the portion you actually use. That portion is calculated using depreciation-the difference between the vehicle's initial price and its projected residual value at the end of your contract. Alongside this core cost, your monthly payment will include an interest charge referred to as the money factor, standard administrative fees, and any applicable taxes. Most standard agreements also incorporate an annual mileage limit, commonly between 10,000 and 15,000 miles, which is designed to protect that final expected residual value.
What this means for local drivers is a more predictable transportation budget with built-in flexibility. If you frequently navigate the busy US‑30 corridor in Merrillville or make regular weekend trips up to Michigan City, leasing provides a streamlined way to step into updated driver-assistance and safety technology every couple of years. Because you are financing a temporary drop in value rather than the entire purchase price of the car, your monthly out-of-pocket expenses are generally lower than they would be with a traditional auto loan.
Navigating Your Chevrolet Lease-End Options
As your Chevrolet lease approaches its final months, you generally have three paths forward: buying the vehicle outright, upgrading to a new model, or simply returning it. What this means for Northwest Indiana drivers is that you aren't locked into a single outcome if your daily routine has changed-whether you suddenly need extra cargo room for shopping trips at Southlake Mall, or you've decided your current Silverado 1500 is already the perfect fit for your daily commute down US-30. For instance, comparing the residual value listed in your original contract to current market estimates on Kelley Blue Book can quickly reveal if buying out your lease is the smartest financial move.
- Purchase Your Leased Chevrolet: You can buy your car, truck, or SUV for the exact residual amount established at the start of your term. Since this buyout price was locked in on day one, you bypass current market fluctuations and dealership haggling entirely.
- Upgrade to a New Model: If you want the latest safety features or your lifestyle demands a different setup, turn in your current vehicle and start a fresh agreement. Swapping a smaller vehicle for a spacious Chevrolet Traverse, for example, makes a lot of sense if your family needs three rows of seating for weekend outings to Hidden Lake Park.
- Turn In Your Vehicle: You always have the option to hand over the keys and walk away. Just make sure to schedule a pre-return inspection roughly 60 to 90 days before your lease maturity date, which gives you plenty of time to address any excess wear, tear, or mileage overages before turn-in.
Financing vs. Leasing: Which Path Makes Sense for Your Chevrolet?

The primary difference is ownership. Financing a Silverado 1500 means you will eventually own it outright, making it ideal if you log heavy mileage commuting along US-30. Conversely, leasing typically involves a 24- to 36-month term where you only pay for depreciation. For Merrillville drivers, this dictates whether you prioritize long-term equity or short-term flexibility.
| Feature | Financing a Chevrolet | Leasing a Chevrolet |
|---|---|---|
| Ownership | The title officially transfers to you once the auto loan is fully paid off. | The lessor retains ownership; you are simply paying for the right to drive it. |
| Monthly Payments | Generally higher, as your payments go toward the entire purchase price plus interest. | Often lower because you are only financing the expected depreciation during the lease term. |
| Upfront Costs | A down payment is strongly recommended to reduce your overall loan balance and interest. | Typically requires the first month's payment, registration, and an acquisition fee to drive off. |
| Customization | Complete freedom to install aftermarket accessories, lift kits, or heavy-duty bed liners. | The vehicle must be returned in its factory configuration; modifications are generally prohibited. |
| Mileage | No restrictions-perfect for frequent road trips or long commutes across Lake County. | Annual caps typically range from 10,000 to 15,000 miles, with per-mile fees applied to overages. |
| Wear & Tear | Scratches and dings will simply lower the vehicle's future trade-in or resale value. | You will be charged excess wear-and-tear fees for significant dents, glass damage, or interior stains. |
| End of Term | Keep driving payment-free, sell the vehicle privately, or trade it in for a newer model. | Turn the keys in, purchase the vehicle at its predetermined residual value, or lease a brand-new Chevrolet. |
What Shapes Your Chevrolet Lease and Loan Terms?
When structuring a payment plan, several moving parts dictate the final numbers you see on paper. For drivers in Merrillville, balancing these variables is the key to keeping your monthly budget comfortable while handling daily commutes along the US-30 / Interstate 65 corridor. Lenders evaluate a mix of your personal financial history and the specific vehicle you want to drive home. Here is a breakdown of what influences your approval and rates.
- Credit Score History: Lenders review your credit profile to determine risk and assign interest rates. A higher tier score usually unlocks the most competitive rates, substantially reducing the total cost of borrowing.
- Initial Down Payment: Bringing cash or a trade-in to the table lowers the principal loan amount. For instance, aiming for a 20% down payment shrinks your monthly obligation and cuts down the total interest you will pay over the years.
- Length of the Term: The duration of your contract changes the math completely. Stretching a loan from 60 to 72 months lowers your immediate monthly bill, but you end up paying more total interest. On the flip side, a standard 36-month lease typically offers a lower monthly cost than buying, though you return the vehicle at the end.
- Vehicle Choice and Price: The exact model you pick influences the terms. A brand-new Chevrolet Silverado 1500 Gas model might feature special manufacturer APR promotions or lease incentives that are not available for older pre-owned inventory.
- Debt-to-Income (DTI) Ratio: Banks compare your current monthly debt obligations to your gross income. A lower DTI gives lenders confidence that adding a car payment for weekend trips to Southlake Mall won't strain your finances, making it easier to secure favorable terms.
Can I Qualify for Special Chevrolet Discount Programs?
If you're looking to get behind the wheel of a new vehicle, you might be eligible for factory-backed savings that directly lower your bottom line. For families running daily errands around Southlake Mall or professionals commuting along the US-30 corridor, these financing and lease programs make upgrading to a safer, more modern ride significantly more accessible. We always recommend verifying the latest national parameters on Chevrolet's official site, but here is a breakdown of the core incentive categories you can typically apply toward your next purchase.
- Chevrolet College Discount: Recent alumni-and in many cases, current college students nearing their degree-can often secure a specialized rebate. You generally just need to provide your recent diploma or official transcripts alongside proof of current or upcoming employment.
- Chevrolet Military Cash Allowance: Active duty military personnel, reservists, retirees, and veterans within a specific window of discharge (along with their spouses) are frequently eligible for targeted cash allowances. It is a straightforward way to save, particularly for service members commuting out toward Gary Regional Airport or nearby installations.
- Owner Loyalty Benefits: Already have a Chevy parked in your garage? Current owners frequently receive lease cash or financing reductions when staying in the brand family. This means trading in an older gas model for a new Equinox EV could unlock exclusive retention bonuses.
- Lake County Regional Promotions: Incentives fluctuate based on seasonal events or local market conditions across Northwest Indiana. For example, a winter sales event might introduce heavier lease incentives on an all-wheel-drive Tahoe just in time for snowy, unpredictable drives to Hidden Lake Park.
How Do I Apply for Chevrolet Financing or a Lease?
Securing an auto loan or lease for a new Chevrolet Equinox or Silverado 1500 doesn't have to take all afternoon. For families running errands around Southlake Mall or professionals commuting along the US-30 corridor, getting your financial paperwork organized ahead of time means less waiting and more driving. Knowing your rate upfront saves you hours at the desk, so you can spend that time enjoying your new vehicle. Here is the straightforward process to get your application moving quickly.
- Get Pre-Qualified: Start by checking your potential interest rates and terms online. This early step uses a soft credit check, meaning you can explore your budget options without lowering your credit score.
- Gather Documents: Before you head out, collect your valid driver's license, recent proof of income (such as your last two pay stubs), proof of Lake County residence (a recent utility bill works perfectly), and active auto insurance information.
- Complete the Official Application: Once you narrow down the exact vehicle you want, you will submit a formal application. Submitting this official paperwork requires a hard inquiry on your credit report to lock in your final lender approval.
- Review & Sign: Carefully examine your final APR, exact monthly payment, and loan duration (for example, comparing how a 60-month term changes your payment versus a 72-month term). Verify any added vehicle service contracts, sign the paperwork, and head home down Broadway (State Road 53).
Paying Cash vs. Financing Your Next Chevrolet
Deciding how to pay for your next vehicle generally comes down to balancing your monthly cash flow with your long-term savings. For drivers commuting along the busy US-30 and Interstate 65 corridor in Lake County, paying cash outright has one massive advantage: immediate ownership. When you hand over a check for a new Chevrolet Equinox, you completely eliminate monthly car payments and avoid paying a single cent in interest. That said, dropping a large lump sum all at once dramatically reduces your liquid savings. Emptying your bank account to buy a vehicle might save you money on interest, but leaving yourself short if a home furnace breaks down during a harsh Indiana winter isn't always practical.
Financing, on the other hand, lets you keep your emergency fund intact by spreading the vehicle's cost out over several years. If you decide to finance a roomy Chevrolet Traverse for weekend family trips to Southlake Mall, you can typically break the purchase down into a standard 36- to 72-month term. This approach means you hold onto your cash reserve for daily life in Merrillville, even though you will ultimately pay more over the life of the loan due to interest charges. For most buyers, the right choice simply depends on what brings the most peace of mind: enjoying a life totally free of car payments, or taking on a structured loan to keep cash accessible for other priorities.
Weighing the Pros and Cons of Each Payment Method
Deciding between buying and leasing comes down to your daily mileage, long-term goals, and budget. Whether you're making a quick run to Southlake Mall or handling a long highway commute down the US-30 corridor, comparing these tradeoffs ensures your new Chevrolet fits exactly how you live and drive.
Pros of Financing a Chevrolet
- Total Ownership: Once that final payment clears, the title is yours to keep, sell, or hand down to a new driver in the family.
- No Mileage Caps: Drive freely across state lines to Chicago or run endless local errands in Crown Point without worrying about tracking miles or facing overage penalties.
- Freedom to Customize: If you want to add an aftermarket bed liner to your Silverado 1500 or upgrade the wheels on your Tahoe, you have complete control over modifications.
- Building Long-Term Equity: Every monthly payment increases your financial stake in the vehicle, giving you solid trade-in value when you are eventually ready for an upgrade.
Cons of Financing a Chevrolet
- Higher Initial Payments: Because you are paying off the entire purchase price of the vehicle, the monthly payments typically run higher than a lease for the exact same model.
- Long-Term Maintenance Responsibilities: Once the standard 3-year/36,000-mile Bumper-to-Bumper Limited Warranty expires, you handle the cost of unexpected repairs unless you opt for an extended protection plan.
- Market Depreciation: While you do build equity over time, the vehicle's overall resale value will naturally decline as age and mileage accumulate.
Pros of Leasing a Chevrolet
- Lower Monthly Cost: Since a lease only charges you for the vehicle's expected depreciation during the contract-not its full MSRP-your monthly bill is usually noticeably lighter.
- Warranty Alignment: Most lease terms last two to three years, meaning you are almost always covered by Chevrolet's factory 3-year/36,000-mile Bumper-to-Bumper coverage, minimizing out-of-pocket repair costs.
- Frequent Upgrades: Leasing allows you to step into a brand-new Equinox or Traverse every few years, ensuring you always have the latest safety technology for those icy winter drives to Hidden Lake Park.
- Zero Resale Stress: At the end of your contract, you simply hand the keys back to the dealership. There is no need to haggle over trade-in values or search for a private buyer.
Cons of Leasing a Chevrolet
- Zero Built-In Equity: Because you are essentially renting the vehicle from the manufacturer, you don't own a physical asset at the end of the term to use toward your next down payment.
- Strict Mileage Limits: Leases typically cap your driving at 10,000 to 15,000 miles annually. If your daily commute from Schererville adds up fast, you could face per-mile penalty fees at turn-in.
- Wear and Tear Charges: You must return the vehicle in excellent condition. Significant body dents, excessive interior stains, or scratched rims can trigger extra fees.
- Modification Restrictions: The vehicle must remain in its original factory state, meaning permanent changes-like custom paint jobs or heavy-duty towing modifications-are strictly off-limits.
Smart Strategies for Negotiating Your Chevy Purchase

Securing a fair price on a dependable Chevrolet shouldn't involve guesswork. For drivers commuting from Valparaiso or tackling weekend shopping runs near Southlake Mall, locking in a favorable financial structure translates directly to a healthier monthly budget. The most effective way to minimize your total out-of-pocket expense is to separate the vehicle's actual cost from the loan or lease terms before you even sit at the desk. By organizing your credit profile and familiarizing yourself with industry terminology, you put yourself in the driver's seat during the entire process.
- Review Your Credit Report Early: Take time to clear up any discrepancies on your credit history before submitting applications. A slight bump in your score can drastically lower your APR on a standard 60-month loan, which fundamentally changes the total amount you end up repaying.
- Compare Financing Rates: Don't assume the first offer is your only option. Gather pre-approvals from a local Lake County credit union or bank, then compare those numbers against the dealership's current rates to secure the lowest possible interest.
- Focus on the Bottom Line First: Whether you want a spacious Chevrolet Traverse for school carpools or a rugged Colorado for weekend projects, negotiate the final purchase price independently. Avoid mixing trade-in values or monthly payment targets into this initial conversation, and consult Kelley Blue Book or Edmunds to understand fair market valuations.
- Time Your Visit Wisely: Dealerships and manufacturers often roll out specific incentives at the end of the month, quarter, or when transitioning to the newest model year. Paying attention to the calendar can unlock unique rebate opportunities.
- Decode Leasing Vocabulary: If you plan to lease a Chevrolet Equinox EV for those daily commutes down Broadway (State Road 53), you need to know the jargon. "Capitalized cost" refers to the negotiated vehicle price, "residual value" is what the SUV is projected to be worth at lease-end, and the "money factor" acts as your interest rate.
- Factor in Standard Protections: When calculating your long-term budget, remember that every new Chevrolet includes a 3-year/36,000-mile Bumper-to-Bumper Limited Warranty and a 5-year/60,000-mile Powertrain Limited Warranty. Knowing what is already covered helps you decide if buying an optional extended vehicle protection plan makes financial sense for your driving habits.
Frequently Asked Questions (FAQs)
How does Chevrolet of Merrillville handle warranty claims and customer feedback?
Our dedicated team, backed by Andy Mohr Automotive, works straightforwardly to ensure you remain fully informed during any service visit. Since opening our doors in 2005, we have prioritized transparent, professional support to seamlessly handle your vehicle's needs, giving you peace of mind during snowy winter commutes along the I-65 corridor.
What should I know before leasing a vehicle from Chevrolet of Merrillville?
As a family-owned dealership, Chevrolet of Merrillville provides no-haggle pricing alongside our “We'll Beat Any Offer, Guaranteed” promise on your new vehicle. Our staff will present tailored incentives for college graduates and military members to fit your middle-income budget, keeping those 32-minute solo drives down US-30 affordable and stress-free.
How can I clarify lease terms before signing?
The professionals at Chevrolet of Merrillville will review your agreement with you step by step, utilizing our straightforward approach to answer every question. We also offer tools like personalized video walkarounds and a virtual showroom so families planning trips to Southlake Mall can finalize their paperwork with absolute clarity.
How does Chevrolet of Merrillville ensure a seamless and transparent leasing process?
Chevrolet of Merrillville eliminates the usual guesswork by strictly offering clear, no-haggle pricing and consistently dedicating our staff to professional, transparent communication. We manage every step alongside you to deliver a highly convenient experience, leaving you more time to enjoy weekend outings at Hidden Lake Park.
What amenities does Chevrolet of Merrillville offer for families and pets?
Chevrolet of Merrillville maintains a welcoming, customer-centric environment complete with a pet-friendly showroom and a dedicated children-friendly waiting area. Our layout guarantees a comfortable, seamless visit for local families who need a convenient break from shopping at nearby national retailers or running regional errands.
How does Chevrolet of Merrillville make the car-buying experience convenient?
Our team embraces modern technology by giving you access to a virtual showroom, personalized video walkarounds, and seamless home delivery options. We specifically created these customer-centric solutions to assist healthcare and manufacturing professionals who face busy schedules and need dependable transportation for winter travel to Turkey Creek Trail.
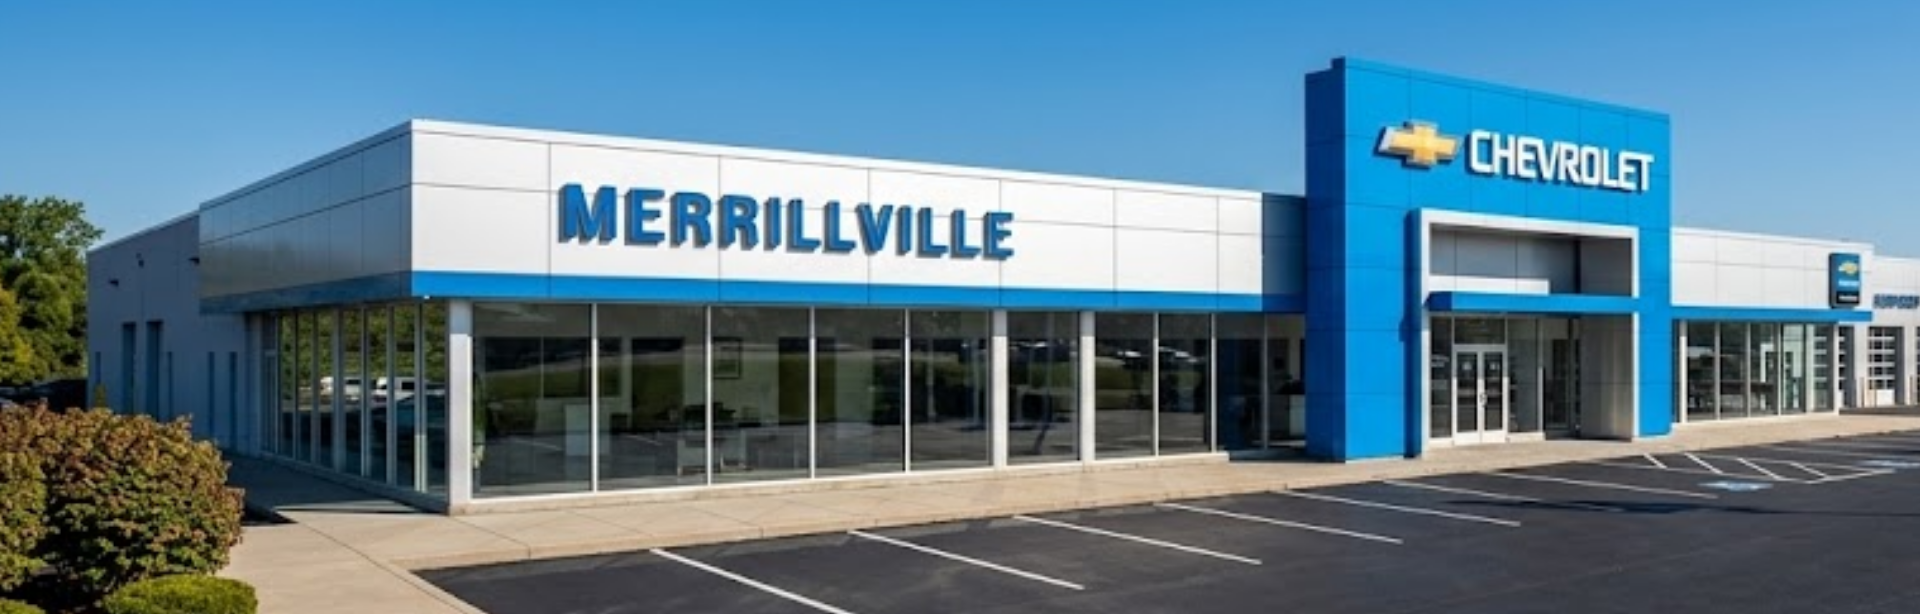
About Chevrolet of Merrillville
At Chevrolet of Merrillville, we've proudly been a part of the community since 2005, bringing you a car-buying experience that's as transparent as it is convenient. As a family-owned dealership backed by Andy Mohr Automotive, our commitment to you is reflected in our no-haggle pricing, “We'll Beat Any Offer, Guaranteed” promise, and a wide array of customer-centric amenities. From personalized video walkarounds to home delivery and our virtual showroom, we've embraced technology to make your journey with us seamless and enjoyable. Our dedicated team, consistently praised for their professionalism and straightforward service, is here to ensure you feel valued and informed every step of the way. Whether you're a college graduate, a military member, or simply a loyal customer, we offer tailored incentives and a welcoming environment, complete with a pet-friendly showroom and a children-friendly waiting area, to make your visit exceptional.Related Articles:
Finding the Right Chevrolet Dealer in Merrillville, IN: A Comprehensive Guide